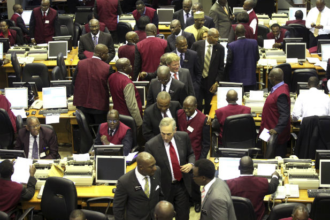
26 Nigerian banks are focusing on capital markets and investment platforms to strengthen their financial stability and resilience.
The Central Bank of Nigeria has directed commercial banks with international authorization to increase their capital base to N500bn, national banks to N200bn, and non-interest banks to increase their capital to N20bn and N10bn.
The apex bank circular mandates banks to meet a minimum capital requirement within 24 months. Five major banks are raising N1.36 trillion in capital markets, with Zenith Bank planning to raise N290 billion, Fidelity Bank expanding its capital raising, Access Holdings raising N351 billion, and Guaranty Trust Holding Company seeking N400.5 billion.
FCMB Group has launched a public offer to raise N110.9bn through 15.197bn shares at N7.30 per share, with a three-phased approach to raising to N397bn to drive diversification plans. The group plans to incorporate a technology holding company by 2026.
The Nigerian Central Bank uses a unique definition of minimum capital.
Banks must raise funds to maintain their licenses, using strategies like social media influencers to attract investors. However, investors should be aware that their investments can yield dividends or significant losses, and patience is crucial for making informed decisions. Financial experts emphasize the importance of careful evaluation.
Customers should consider indices like CaR ratios to make informed investment decisions, as a higher ratio indicates a stronger capacity to absorb potential losses.
Evaluate bank assets, especially loan portfolios, for potential risk and stay informed about regulatory changes and government policies impacting the banking sector’s stability and profitability.
Bank profitability metrics like return on equity and dividend policies reveal operational efficiency and profitability. Analyzing funding sources and management quality is crucial for assessing a bank’s financial health and ability to generate cash flow.
Investors should evaluate a bank’s market position and competitive advantages, as banks with strong positions attract capital and customers, enhancing their stability and growth potential.
Risks to avoid: Avoid investing in banks involved in mergers and acquisitions, as they may introduce uncertainties and risks, potentially affecting investor returns and affecting the bank’s performance and stability.
Be financially informed: Monitoring the broader economic environment, including interest rates, inflation, and growth, is crucial for assessing the performance of the banking sector during recapitalization.
Don’t overlook the status: Former President of the Chartered Institute of Bankers of Nigeria and professor of economics, Prof. Segun Ajibola, suggests that tier-one banks are generally better investments due to their stability and lower likelihood of adverse events. He believes that investors can choose shares from these banks based on their consistent performance history. Tier 2 banks are likely to meet the new capitalization base, while Tier 3 is a risk. Investing in banks with broad ownership, such as Wema Bank, can help avoid liquidation issues. It’s crucial to monitor bank performance over time.
Management structure: The don advises investors not to invest heavily in banks with limited ownership and broad operations. He suggests comparing regional banks to international ones based on performance, dividends, and appreciating shares. Charles Sanni, CEO of Cowry Treasurers Limited, emphasizes value as a key index.
Check their track record: To invest in banks, consider their track records, financial performance, and market opportunities. Ensure you see an upside based on forecasts or value as a shareholder. Assess earnings per shareholder or dividends per shareholder in the past. Check their dividend payout ratio to ensure good earnings are distributed.
Corporate governance structure: Sanni suggests customers should assess an entity’s corporate governance culture, considering its level of supervision under the central bank. This confidence in the company’s ability to raise funds and capital is crucial. Additionally, customers should examine their non-performing loan portfolio. The loan-to-deposit ratio is crucial in determining the risk-return ratio of equities. The Director of Research and Strategy at Chapel Hill Denham, Tajudeen Ibrahim, advises investors to consult professionals to determine suitable banks and be aware of current market offers when investing in equities.